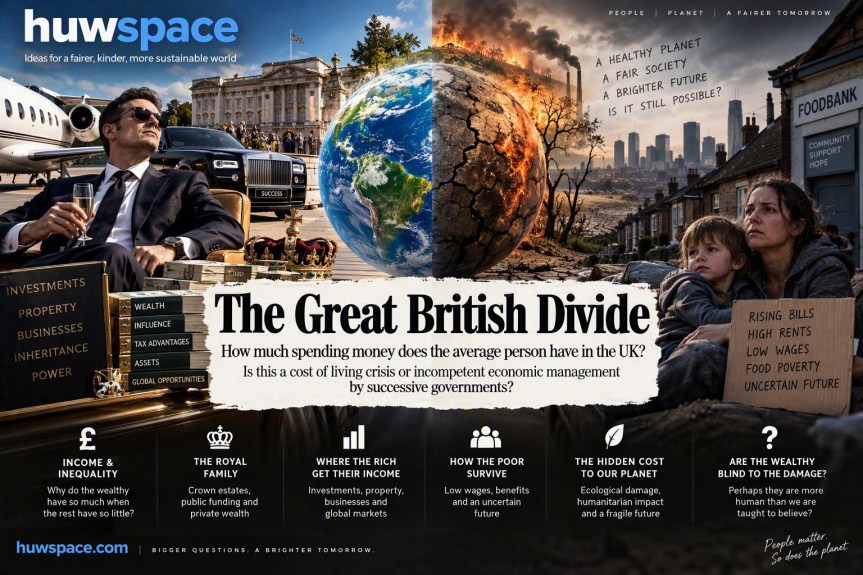
When millions of people are counting pennies before payday while a growing number of individuals accumulate wealth measured in millions or even billions, it raises an uncomfortable question. Is Britain’s cost of living crisis simply the result of bad luck and global events, or is it the consequence of decades of economic decisions made by successive governments?
A Nation Under Pressure
For many people across the United Kingdom, the term “cost of living crisis” has become part of daily life. Rising prices, increasing rents, higher mortgage payments, elevated energy bills and expensive food have squeezed household budgets to breaking point.
The average UK household has an equivalised disposable income of around £32,300 per year after direct taxation, but this figure masks a much harsher reality. Once housing, utilities, transport, food and other essentials are paid for, many households are left with very little genuinely discretionary income.
The difference between statistical averages and lived experience is enormous. Someone earning a reasonable salary in London, Bristol or Manchester may still struggle to save, while a person on a lower income may be one unexpected bill away from financial crisis.
The result is that many people no longer feel poor in the traditional sense. Instead, they feel permanently insecure.
Cost of Living Crisis or Economic Mismanagement?
The answer is probably both.
There is little doubt that global events have played a major role. The pandemic disrupted global supply chains, energy markets became volatile following international conflicts, and central banks increased interest rates to tackle inflation. These events affected economies across the world.
Yet many economists argue that Britain’s problems run much deeper. Years of austerity, sluggish productivity growth, weak business investment, housing shortages and the economic friction associated with Brexit left the UK particularly exposed when global shocks arrived.
The uncomfortable truth is that successive governments of all political colours share responsibility.
Conservative governments often prioritised fiscal restraint and market-led solutions. Labour governments generally increased spending on public services but rarely challenged the fundamental structures driving wealth inequality. Neither side fundamentally altered a system that increasingly rewards those who own assets rather than those who rely solely upon wages.
As a consequence, Britain has experienced years of relatively weak wage growth while asset values, particularly housing and investments, have surged.
The Two Economies of Modern Britain
Britain increasingly resembles a country operating two separate economies.
The first economy belongs to those whose wealth comes primarily from work.
The second belongs to those whose wealth comes primarily from ownership.
The distinction is crucial.
If you stop working, your income stops.
If you own enough assets, your income continues regardless.
This is perhaps the single most important factor explaining why the rich have become richer while many ordinary households have struggled.
How Millionaires Make Their Money
Many people imagine the wealthy earning extraordinary salaries. While some do, the UK’s richest individuals increasingly derive their income from ownership rather than employment.
Investment Income
Shares in companies provide dividend payments.
A millionaire with a substantial investment portfolio may receive thousands or even millions of pounds annually without performing any additional work. As businesses grow and generate profits, shareholders benefit.
Business Ownership
The wealthiest individuals frequently own businesses outright or hold significant stakes within them.
Rather than receiving wages alone, they benefit from dividends, retained profits and increases in company valuation.
Property and Land
Property remains one of the greatest engines of wealth creation in Britain. Research highlighted in the source document notes that property is among the largest sources of wealth for the richest households. Income can be generated through commercial rents, residential portfolios and land development.
While renters see housing as a monthly expense, landlords often see it as a monthly income stream.
Capital Gains
Another key advantage available to wealthy individuals is asset appreciation.
Stocks, property and land often increase in value over time. When these assets are sold, significant profits can be realised through capital gains, which have historically often been taxed differently from employment income.
In simple terms, many wealthy people earn money while they sleep because their assets continue working on their behalf.
The Royal Family: A Different Kind of Wealth
No discussion about wealth in Britain would be complete without examining the position of the monarchy.
The Royal Family occupies a unique financial position that combines public funding, historic land ownership and private wealth.
The Sovereign Grant
Official royal duties are funded through the Sovereign Grant, which reached approximately £137.9 million according to the source document. This funding mechanism is linked to profits generated by the Crown Estate.
Historic Estates
The Duchy of Lancaster provides private income to the King, while the Duchy of Cornwall provides income to the heir to the throne. These large property portfolios generate substantial revenues through land, commercial property and other investments.
Private Wealth
The monarchy also benefits from privately owned estates, inheritance and investments accumulated across generations.
Supporters argue that the monarchy contributes economically through tourism, diplomacy and national identity.
Critics argue that it represents one of Britain’s clearest examples of inherited privilege and concentrated wealth.
Regardless of which side one supports, the Royal Family demonstrates how ownership of land and assets remains a powerful source of long-term financial security.
How the Poorest Survive
At the other end of society, the financial picture looks entirely different.
The poorest households generally possess little or no asset wealth and instead depend almost entirely upon wages, benefits or both.
Low-Paid Employment
Many people experiencing poverty are working.
They often work in retail, hospitality, social care, logistics or other service-sector occupations where wages remain relatively low and employment can be insecure. Zero-hours contracts and gig economy arrangements can leave workers uncertain about future earnings.
State Support
Benefits including Universal Credit, housing support and disability payments provide essential lifelines for many households. These payments frequently prevent extreme hardship rather than providing financial comfort.
No Assets, No Cushion
One of the most important differences between rich and poor is resilience.
When wealthy households face setbacks, they often have savings, investments, property or other resources to draw upon.
The poorest households frequently have no such safety net. The source document notes that the lowest wealth groups possess little wealth and often receive no income from investments, dividends or property ownership.
Every financial shock becomes a crisis.
Why the Gap Keeps Growing
The widening divide is not simply about income.
It is about ownership.
Wages have generally grown far more slowly than asset prices over the past several decades. Someone who bought a property twenty or thirty years ago may have accumulated hundreds of thousands of pounds in wealth through rising house prices alone.
Meanwhile, younger generations face higher housing costs, higher rents and larger barriers to asset ownership.
The result is a cycle where:
- Asset owners accumulate more wealth.
- Their wealth generates additional income.
- That income purchases more assets.
- The cycle repeats.
Those without assets remain dependent on wages that often struggle to keep pace with inflation.
So Who Is to Blame?
The honest answer is that there is no single villain.
Global events have clearly contributed to the current squeeze on household finances.
However, it would also be difficult to argue that three decades of economic policy have consistently prioritised broad-based prosperity. Housing shortages, rising inequality, weak productivity growth, stagnant wages and increasing asset concentration have developed over many years and under multiple governments.
The cost of living crisis may therefore be less a temporary crisis and more a symptom of deeper structural problems.
Conclusion: A Question of Wealth, Not Just Income
Perhaps the most important question facing Britain is not how much people earn, but what they own.
The UK’s richest individuals often derive income from investments, businesses, property and inherited assets. The poorest depend primarily upon wages and state support. The Royal Family occupies a unique middle ground of public funding, historic landed wealth and private assets.
When one group’s money works for them while another group’s survival depends entirely on selling their labour, inequality becomes almost inevitable.
The debate should therefore move beyond the cost of living and towards a broader discussion about wealth creation, ownership, housing, taxation and economic opportunity.
Because if millions of working people are finding that hard work no longer guarantees financial security, then Britain’s challenge may not simply be a cost of living crisis.
It may be a wealth distribution crisis decades in the making.
There might be no villains but their certainly are humans that should be held to account for their actions or lack of action.
If the wealthy are truly more intelligent, strategic and far-sighted than everyone else, why has the world accumulated unprecedented debt, ecological decline, biodiversity collapse, housing shortages and widening inequality under their stewardship or ownership? Perhaps the answer is not that they are evil, nor uniquely wise. Perhaps they are simply human. Exceptionally successful humans, certainly, but humans nevertheless. Capable of remarkable innovation and extraordinary blindness in equal measure.
There is a common assumption that the wealthy are rich because they are uniquely insightful, rational or far-sighted. If that were entirely true, we might expect them to be the first people to recognise threats such as climate change, biodiversity collapse, social instability, resource depletion and growing inequality.
Yet history suggests something different.
Many wealthy individuals and institutions are exceptionally skilled at navigating the existing economic system. That is not necessarily the same as understanding the long-term consequences of that system.
A hedge fund manager may understand financial markets brilliantly while having little understanding of ecological systems. A property developer may understand land values but not biodiversity. A technology entrepreneur may understand innovation but underestimate social disruption. Wealth often indicates expertise in a specific domain, not universal wisdom.
The deeper irony is that many of the world’s richest people have become wealthy through activities that depend upon stable societies, functioning ecosystems and long-term public trust. Yet the incentives of modern capitalism often reward short-term gains over long-term sustainability.
This creates what economists call a “tragedy of the commons”.
An individual corporation can profit by extracting more resources, cutting costs or maximising returns. However, if every corporation behaves this way simultaneously, the collective outcome may be environmental degradation, social fragmentation and political instability that ultimately harms everyone, including the wealthy.
The problem may not be greed alone.
It may be human nature.
We often imagine the ultra-wealthy as somehow different from ordinary people. In reality, billionaires and monarchs are still subject to the same psychological biases as everyone else:
- They favour short-term rewards over distant risks.
- They become accustomed to their circumstances.
- They seek confirmation of existing beliefs.
- They surround themselves with people who share similar worldviews.
- They struggle to imagine systemic collapse because they have rarely experienced vulnerability.
In that sense, their blindness may not demonstrate superhuman cunning but very human limitations.
The Roman aristocracy did not prevent the decline of Rome.
European nobility did not foresee the French Revolution.
Industrialists often ignored pollution until rivers caught fire and cities became unliveable.
Financial elites repeatedly failed to predict economic crashes despite possessing enormous expertise.
Intelligence does not eliminate human frailty.
In fact, wealth can sometimes insulate people from reality. Rising food prices, failing public transport, overstretched healthcare and deteriorating housing conditions are often experienced first and most intensely by ordinary citizens. Those with wealth can frequently buy alternatives, delaying their awareness of wider social problems.
There is also a moral question.
If someone can see the damage and continues anyway, that is one issue.
If they genuinely cannot see the damage because they have become detached from the consequences of their actions, that is another.
Both are troubling, but the second possibility may be more common than we like to admit.
The uncomfortable conclusion is that wealth may be a measure of success within a system, but it is not necessarily a measure of wisdom about whether that system is sustainable. The richest people in society may understand how to win the game, while remaining surprisingly poor at recognising when the game itself is putting both theirs and our future at risk.


