For generations, banking was built on relationships. Customers knew the people behind the counter, local branches were part of the community, and major financial decisions were discussed face-to-face with trained professionals. Today, many customers increasingly feel that those values are being sacrificed in the pursuit of higher profits and lower operating costs and those customers are right.
Record Profits, Vanishing Service
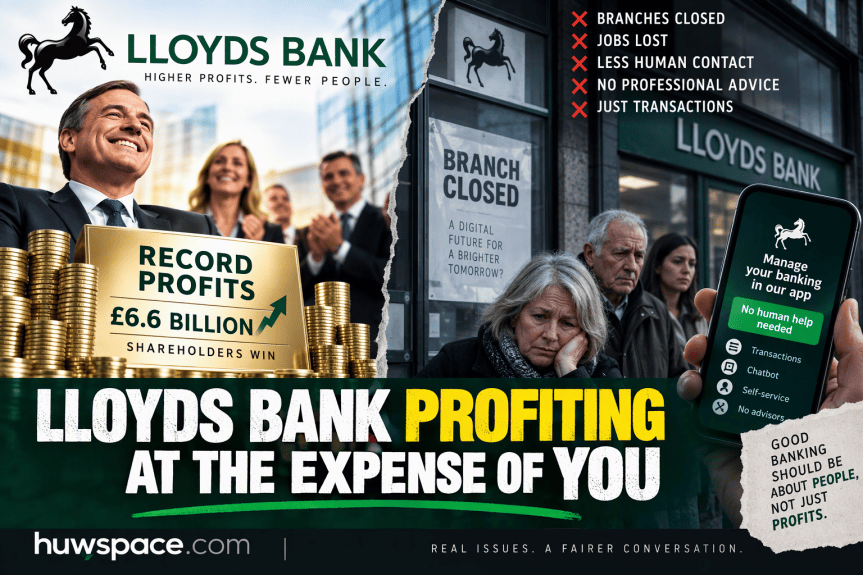
Lloyds Bank reported statutory pre-tax profits of £6.6 billion during the first nine months of 2026, representing a substantial increase on the previous year. Much of that growth was driven by higher interest income generated during a period of elevated interest rates.
On paper, shareholders have reason to celebrate.
For many staff and customers, however, the picture looks rather different.
Tracking a running, multi-decade total of exact redundancies is challenging because banks record reductions through complex channels: formal compulsory redundancies, voluntary severance packages, and natural attrition (not replacing workers who leave).
However, looking at structural headcount data reveals a stark transformation: Since its post-financial crisis peak in 2009, Lloyds Bank has permanently eliminated over 47,000 positions, shrinking its workforce by approximately 44%. If looking strictly at traditional, branch-facing customer advisory roles over a full 30-year trajectory, retail union data indicates that well over 70% of those specific frontline positions have been permanently dissolved as the bank prioritises transactions over relationships.
Across the country, branches continue to disappear, staffing levels are reduced, and the availability of face-to-face support is becoming increasingly rare. Critics argue that ordinary customers are paying the price for a business strategy built around cost reduction, automation and digital-first banking.
The contrast is difficult to ignore. At a time when household budgets remain under pressure, banks are generating billions in profits while simultaneously removing many of the services that once justified their presence on Britain’s high streets.
From Banking Relationships to Transaction Processing
There was a time when banks did much more than process payments.
Customers could walk into a branch and speak to someone who understood mortgages, savings, investments and personal circumstances. Banking was about advice, guidance and trust.
Today, many customers feel they are no longer treated as individuals but as transactions.
As digital banking expands, physical interaction is increasingly being replaced by apps, automated systems and chatbots. The result is a growing perception that banks are moving away from relationship-based banking and becoming little more than transaction-processing platforms.
While technology undoubtedly offers convenience, convenience is not the same thing as service.
Checking a balance on a mobile phone is easy. Discussing a bereavement, resolving fraud, arranging a complex mortgage or dealing with financial hardship is not. Those situations require empathy, judgement and human understanding.
The Disappearance of Professional Advice
Perhaps the greatest concern is the gradual removal of experienced advisors from local branches. The staff will even in form you over the phone not to bother going into a branch if you need financial advice and guidance there is no one there now to guide or advise and they are profiting from this attitude.
Many Lloyds branches now primarily focus on basic transactions while customers requiring more detailed assistance are often directed towards digital channels or telephone services. The expectation appears to be that technology can replace much of the personal interaction that once defined retail banking.
Yet financial decisions are rarely simple.
Buying a first home, planning for retirement, managing an inheritance or recovering from fraud are deeply personal matters. In these moments, people do not want another app notification. They want to speak to a knowledgeable professional who can answer questions, provide reassurance and explain options clearly.
Reducing access to human expertise may improve efficiency metrics, but it risks undermining the very trust upon which banking depends. Some customers are unable and choose not to se online banking apps and they are being punished, side-lined and ignored by Lloyds.
The Customers Being Left Behind
Whilst younger customers may embrace digital services, not everyone can.
Older residents, people with disabilities, those without reliable internet access and individuals facing complex financial challenges often depend heavily on human support. Consumer groups have repeatedly highlighted concerns that these customers are being pushed to the margins by rapid digital transformation.
Long telephone waiting times, chatbot loops and reduced staffing can leave vulnerable customers feeling frustrated and isolated.
For a bank whose success was built upon serving communities throughout the United Kingdom, this poses a serious question:
Who is being left behind in the race towards efficiency?
Lloyds’ Defence
Lloyds would argue that it is responding to changing customer behaviour.
The bank points to increasing use of mobile banking, the high costs of maintaining extensive branch networks and alternative support options such as telephone and digital services. It maintains that customers increasingly prefer to bank online and that resources should follow demand.
There is some truth to this argument but it does not reflect the true nature of commerce and what people need from a banking institution such as Lloyds.
Millions of people do indeed use mobile banking every day and expect digital services to be available around the clock.
The problem is not digital banking itself.
The problem arises when digital banking stops being an option and starts becoming the only option.
A Dangerous Commercial Gamble
Lloyds may believe it is following the future.
It may instead be removing one of its greatest competitive advantages.
Banking products are increasingly similar. Most banks offer mobile apps, online services, current accounts, savings products and credit facilities. The human relationship is often what differentiates one institution from another.
Financial planning from cradle to grave is no longer offered in branch and if every major bank becomes simply another icon on a smartphone screen, customer loyalty becomes fragile.
Switching banks has never been easier. Through the Current Account Switch Service, customers can move elsewhere with minimal effort. If relationships disappear, competitors need only offer a slightly better rate or incentive to attract customers away.
In attempting to cut costs today, Lloyds may be weakening the loyalty that protects its business tomorrow. If Lloyds is reducing its services to mere buttons on an app then this is a service that for those that want or need it will likely be incentivised to go somewhere else.
The Rise of Alternatives
Interestingly, the market may already be responding.
Building societies such as have openly embraced branch-based banking as a competitive advantage, promising customers continued access to local services and human interaction.
Credit unions continue to provide community-focused services delivered by real people. Banking hubs have emerged to restore physical access where branches have closed. Even the Post Office has become an essential lifeline for many communities abandoned by traditional banks.
These developments suggest that while technology may dominate banking transactions, demand for human contact has not disappeared.
Far from it.
Banking Is About People
Technology should enhance customer service, not replace it.
The danger for Lloyds is that in focusing relentlessly on efficiency, digitisation and shareholder returns, it risks forgetting the fundamental purpose of banking: helping people manage some of the most important aspects of their lives.
An app can tell you your balance.
An algorithm can process a payment.
A chatbot can answer basic questions.
But none of them can replace trust, empathy and professional human judgement.
Those qualities remain valuable, regardless of how advanced technology becomes.
The real question facing Lloyds is not whether customers need branches.
It is whether customers still need people.
The answer, despite all the enthusiasm surrounding digital banking, remains overwhelmingly clear.
They do.
What Lloyds may regard as modernisation, many customers increasingly experience as withdrawal. The challenge for the bank is not simply delivering banking services more cheaply. It is proving that banking can remain personal in an age where human interaction is steadily being treated as an unnecessary cost rather than a vital service.


